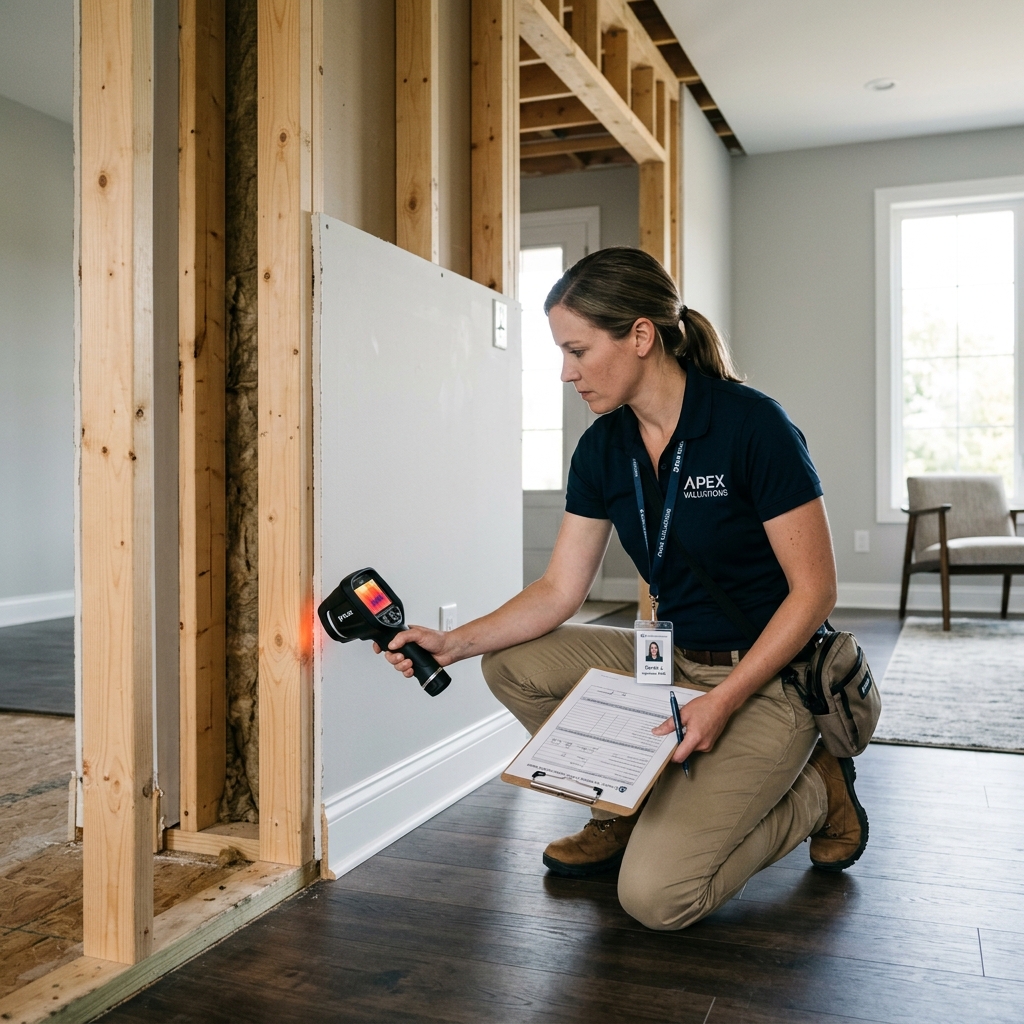
1. Why Appraisers Deduct 10% to 25% for Unresolved Fungal Colonization
Certified real estate appraisers apply substantial 'cost-to-cure' adjustments and environmental stigmatization deductions (frequently reducing property valuations by $25,000 to $75,000) whenever visible mold appears on residential building substrates (such as basement concrete walls, subfloor joists, and attic roof sheathing). Under Fannie Mae.
Certified real estate appraisers apply substantial 'cost-to-cure' adjustments and environmental stigmatization deductions (frequently reducing property valuations by $25,000 to $75,000) whenever visible mold appears on residential building substrates (such as basement concrete walls, subfloor joists, and attic roof sheathing).
Under Fannie Mae Form 1004 guidelines, appraisers classify active biological growth as deferred maintenance that threatens structural durability and buyer habitability.
Mortgage underwriting systems flag low-ball appraisal valuations automatically whenever appraisers check the 'Subject to Repairs' condition box on property appraisal reports.
Uncertified cosmetic remedies (such as applying bleach or brushing Kilz primer over black mold) fail appraiser re-inspections because moisture meters detect underlying dampness within porous timber assemblies.
Mortgage lenders deny loan approvals unless property owners supply certified remediation documentation and third-party laboratory clearance verifying structural restoration.
2. The Mathematical Impact of Cost-to-Cure Penalties on Home Equity
Appraisers calculate cost-to-cure penalties by combining estimated physical remediation expenses with a 10.0% to 15.0% risk discount to reflect market resistance from potential buyers. On a $400,000 residential property, discovering mold behind basement drywall frequently results in a $50,000 appraisal reduction despite.
Appraisers calculate cost-to-cure penalties by combining estimated physical remediation expenses with a 10.0% to 15.0% risk discount to reflect market resistance from potential buyers.
On a $400,000 residential property, discovering mold behind basement drywall frequently results in a $50,000 appraisal reduction despite actual remediation costs totaling only $6,500.
This disproportionate valuation penalty causes loan-to-value (LTV) ratios to exceed lender maximum limits (such as 80.0% on conventional refinances or 96.5% on FHA purchases), forcing buyers to deposit thousands of additional dollars into escrow or abandon the transaction entirely.
Providing verified environmental documentation corrects these exaggerated calculations during formal underwriting appeals.
3. Reversing Property Stigmatization Through Post-Remediation Verification (PRV)
Post-Remediation Verification (PRV) provides verifiable scientific proof that indoor air quality and structural timber returned to Condition 1 normal fungal ecology. An independent Council-certified Indoor Environmental Consultant (CIEC) inspects the containment zone following physical remediation, utilizing 500-lumen halogen lighting to verify zero.
Post-Remediation Verification (PRV) provides verifiable scientific proof that indoor air quality and structural timber returned to Condition 1 normal fungal ecology.
An independent Council-certified Indoor Environmental Consultant (CIEC) inspects the containment zone following physical remediation, utilizing 500-lumen halogen lighting to verify zero visible dust, spores, or water stains remain on framing surfaces.
The environmental consultant collects calibrated bioaerosol air samples at 15.0 liters per minute alongside outdoor baseline controls to analyze fungal spore counts under optical microscopy.
Appraisers eliminate valuation penalties once laboratory reports confirm indoor spore levels remain lower than outdoor baselines, with zero toxic indicator species (such as Stachybotrys chartarum or Chaetomium globosum) detected in living areas.
4. Filing a Formal Reconsideration of Value (ROV) Package
Property owners challenge inaccurate appraisal valuations by submitting a comprehensive Reconsideration of Value (ROV) package directly to the mortgage lender's underwriting department within 5 business days of appraisal receipt. The ROV package contains the licensed contractor's Certificate of Completion stating all work.
Property owners challenge inaccurate appraisal valuations by submitting a comprehensive Reconsideration of Value (ROV) package directly to the mortgage lender's underwriting department within 5 business days of appraisal receipt.
The ROV package contains the licensed contractor's Certificate of Completion stating all work adhered to ANSI/IICRC S520 standards, an itemized Xactimate scope of work, and date-stamped FLIR thermal scans verifying wood moisture levels have normalized below 14.0% WME.
Attaching an AIHA-accredited PRV laboratory report satisfies the Appraisal Management Company (AMC) quality control review, compelling the appraiser to remove condition flags and restore full property market value on the revised appraisal report.
5. Negotiating Appraisal Revisions with Mortgage Lenders
Mortgage loan officers submit the completed ROV package directly to the chief appraiser at the Appraisal Management Company to trigger a formal desk review. Under federal interagency appraisal guidelines, appraisers must review new material factual evidence regarding corrected property conditions within 48.
Mortgage loan officers submit the completed ROV package directly to the chief appraiser at the Appraisal Management Company to trigger a formal desk review.
Under federal interagency appraisal guidelines, appraisers must review new material factual evidence regarding corrected property conditions within 48 to 72 hours of submission.
When presented with third-party laboratory spore trap analysis and contractor completion affidavits, the appraiser issues an amended appraisal report removing all cost-to-cure deductions. This formal adjustment restores the property's original contract valuation, allowing the underwriting team to issue final loan commitment documents without appraisal holdbacks.
6. Restoring Home Equity During Refinancing and Sales
Homeowners executing cash-out refinancing or residential property sales protect tens of thousands of dollars in home equity by eliminating moisture anomalies before appraisers arrive on site. Certified environmental specialists deploy non-destructive moisture meters (such as Protimeter Surveymaster units) to identify hidden plumbing.
Homeowners executing cash-out refinancing or residential property sales protect tens of thousands of dollars in home equity by eliminating moisture anomalies before appraisers arrive on site.
Certified environmental specialists deploy non-destructive moisture meters (such as Protimeter Surveymaster units) to identify hidden plumbing weeping behind bathroom tiles and drywall cavities.
Remediating structural timber with cryogenic dry ice blasting (-109.3°F) and applying EPA-registered botanical fungicidal sealants restores wood framing to pristine condition without generating abrasive residue.
Presenting complete environmental certification packages to Appraisal Management Companies compels appraisers to remove condition flags, approving full market valuations on schedule.
7. Step-by-Step Desk Review Protocol for Appraisal Management Companies
Appraisal Management Companies (AMCs) initiate an internal administrative desk review upon receiving the formal Reconsideration of Value (ROV) petition from the primary mortgage lender. Chief staff appraisers evaluate the third-party Post-Remediation Verification (PRV) certificate against Fannie Mae Selling Guide Section B4-1.
Appraisal Management Companies (AMCs) initiate an internal administrative desk review upon receiving the formal Reconsideration of Value (ROV) petition from the primary mortgage lender.
Chief staff appraisers evaluate the third-party Post-Remediation Verification (PRV) certificate against Fannie Mae Selling Guide Section B4-1.3-06, which governs property condition adjustments and safety remediation requirements.
The reviewing appraiser inspects the certified laboratory spore trap analysis to confirm that indoor bioaerosol concentrations remain below outdoor baseline controls, with zero pathogenic fungal indicator species (such as Stachybotrys or Chaetomium) detected.
When verified laboratory documentation confirms Condition 1 normal fungal ecology, the AMC issues an official addendum removing all 'cost-to-cure' deductions within 48 to 72 hours.
8. Frequently Asked Questions Regarding Mold Appraisal Reductions
How long does an appraiser take to update a revised appraisal report? Appraisers complete formal Reconsideration of Value reviews within 3 to 5 business days after receiving certified Post-Remediation Verification lab reports and contractor completion certificates from the lender.
Can a buyer challenge an appraisal if the seller completed uncertified DIY repairs? Mortgage underwriters reject DIY repairs and will not remove appraisal condition flags unless physical remediation was executed by an IICRC-certified firm with independent third-party clearance testing.
Authored by Antonio
Lead Environmental Health & IICRC Certified Remediation Specialist • Technical Standards Division • Emergency Mold Inspection Network
Related Real Estate & Inspection Guides
Real Estate Guide Failed Home Inspection Due to Attic Mold: How to Save Your Closing in 48 Hours Read Article → Real Estate Guide Mortgage Lender Denied Loan Due to Crawl Space Mold? FHA & VA Clearance Read Article → Real Estate.